The owner's decision
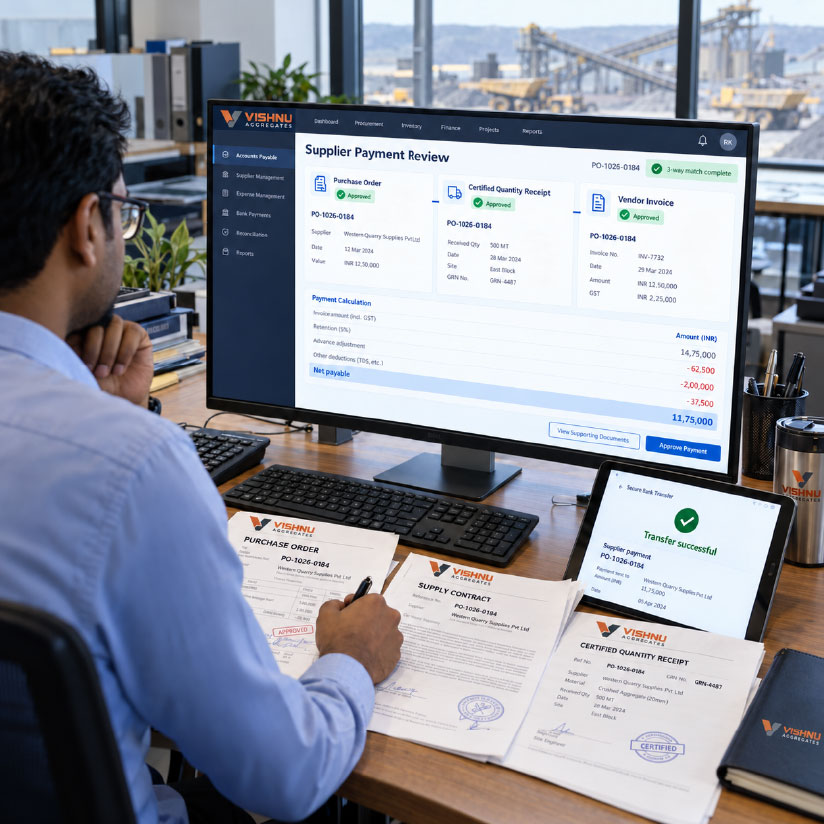
Every owner has to decide how a bill travels from the day it arrives to the day it is paid: receipt, verification, approval, payment. For a supplier, that means connecting the order to the material you actually accepted and then to the invoice. For a contractor, it means connecting the contract to the service that was measured and then to the bill.
Advances, retentions, owner-issued materials, returns and disputed amounts all need to be handled openly rather than absorbed into a rounded figure. In a busy month it is tempting to let the supplier's statement become the only evidence of what is owed. It should never be.
“A payable is the result of agreed work, accepted supply and recorded adjustments. When any one of those is missing, you are not settling an account, you are guessing at it. Every recovery should be explainable to the supplier, the contractor and your own auditor.”
— Super Administrator
Modomines keeps these pieces connected and shows you what is missing or duplicated. The person who certifies the physical work should understand the measurement. Accounts checks the commercial terms and earlier payments. Whoever releases payment needs the authority to do so and confirmation of the intended beneficiary. Together, these checks guard against inflated bills, unrecorded recoveries and diverted payments.
The evidence needed
The trail you rely on includes contract and order versions, quantity certification, acknowledgements, issue and return records, invoice references, applicable taxes, advances and bank evidence.
A material recovery stands on two legs: a contractual basis and an acknowledged quantity and rate. Issuing stock to a contractor is not automatically a purchase by that contractor, and it is not automatically a deduction from every kind of service bill.
The cost of getting it wrong
The mistakes are familiar. An owner pays twice for one invoice, misses a recovery, or pays for parts that never arrived. A contractor is charged for another team's consumption. Someone changes a supplier's bank details, or splits a large bill into smaller ones to slip past review.
Left unresolved, these errors strain the relationship and can halt supply just when the plant needs it most.
That is why the full settlement belongs in Modomines: gross entitlement, authorised additions and deductions, previous payments, the current payment and the remaining balance. Compare supplier and contractor statements periodically. Every adjustment should carry its reason and the name of the person who approved it. And never invent an unsupported "discount" just to make two balances agree.
The applicable state variation
Invoice, tax, withholding, labour and contract requirements differ by transaction, so verify them with your accountant and other responsible advisers. Some rules are national and specific to the transaction, while stamp, establishment or local requirements may vary.
A zero-tax demonstration screen does not establish an exemption, and an item code used inside the software is not automatically a valid statutory classification.
The records that support control
Keep one unbroken line from order or contract to receipt or service certification, then to the bill, recoveries, approval and payment. Show original supplier numbers and flag duplicates visibly. Retain every supplier bank change along with its independent confirmation and the release approval.
Match the bank debit to the intended payable. A prepared voucher does not mean a bill is paid.
Make sure to sample reports through Modomines before relying on it, include partial delivery, partial payment, a returned item, a contractor recovery and a disputed amount. Each one should leave the right stock position, the right payable and a clear audit history.